CFR Incoterms Explained: Cost and Freight
CFR — Cost and Freight — is the Incoterm where the seller pays the ocean freight to the named port of destination, yet the risk of loss transfers to the buyer the moment the goods are loaded on the vessel at the port of shipment. That split — seller pays the freight, buyer carries the sea risk — is the single most misunderstood pairing in container trade, and it is where most CFR disputes are born. For glass packaging buyers it matters twice over: cartons of jars travel long routes, and a broken pallet in a storm is a claim question, not a freight question. At GlassPacker we quote CFR Ningbo or Shanghai as standard for container orders above our 1,000-piece MOQ, with the freight line itemised so buyers can compare it against their own forwarder rates.
What each side pays under CFR
The seller’s bill under CFR runs from the factory gate to the ship’s rail and beyond — in cost terms only. The seller handles export packaging, inland haulage to the port of shipment, export customs clearance, loading charges at origin, and the ocean freight itself to the named destination port, including any bunker and currency surcharges the carrier invoices. The buyer’s bill starts where the seller’s cost duty stops being protective: marine insurance (which the seller has no obligation to buy), unloading and terminal handling at destination unless the freight contract already includes them, import customs, duties, and onward delivery to the warehouse.
The trap is that "Cost and Freight" sounds like door-to-door responsibility. It is not. CFR is a port-to-port cost arrangement with a shipment-point risk transfer. A buyer who reads CFR as "the seller gets it there safely" has mispriced the deal before the first carton leaves the factory.
The risk transfer moment — and the insurance gap
Risk passes from seller to buyer when the goods are placed on board the vessel at the port of shipment (or, for container traffic, when the carrier takes custody at the terminal per the sale contract’s wording). From that second, a container dropped by a crane, a stack collapsed in heavy weather, or seawater ingress is the buyer’s loss — even though the seller chose the carrier and paid the freight.
Who insures under CFR?
Nobody is obliged to. That is the defining gap of CFR: unlike CIF, the seller has no duty to procure marine insurance, and the buyer — who now carries the risk — must arrange cover independently. In practice disciplined buyers place an open cover or voyage policy before the sailing date, naming the CFR shipment and its invoice value plus 10 percent. Buyers who skip this self-insure by default, which for fragile glass cargo is a bet against physics.
The seller’s notice duty
Because the buyer must insure a shipment it cannot see, Incoterms 2020 imposes on the seller a duty to give the buyer sufficient notice that the goods are on board — typically the shipping advice with vessel name, bill of lading number, sailing date and cargo details. A seller who sends the advice late leaves the buyer unable to insure in time; losses in that window can fall back on the seller despite the risk-transfer rule. GlassPacker issues its shipping advice within 24 hours of the carrier’s receipt, with carton counts, gross weight and HS code 7010 so the buyer’s policy can be bound the same day.
Destination costs: unloading, THC and demurrage
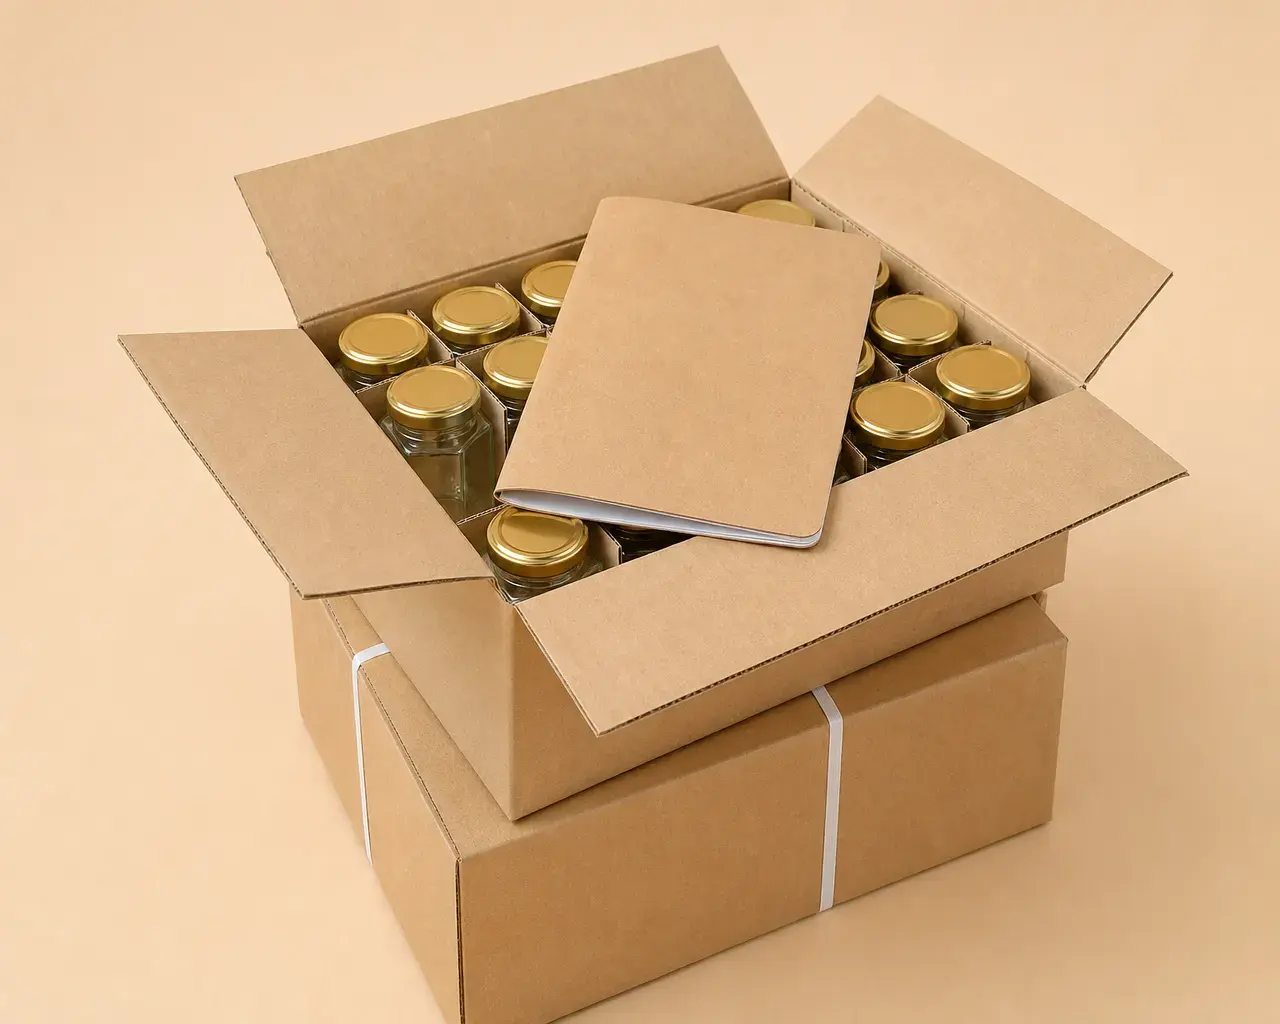
The second classic CFR dispute is who pays at the far end. Ocean freight contracts vary: on liner terms the freight often includes discharge; on charter-derived or "free out" terms it does not, and destination terminal handling charges (THC), discharge labour and wharfage land on the consignee. A buyer who compared two CFR prices without checking the discharge terms may find the cheaper quotation arrives with a four-figure THC invoice.
Demurrage and detention follow the same logic. The seller’s freight buys carriage, not free time at destination; if the buyer’s customs broker is slow, storage and container detention accrue to the buyer’s account. The practical defence is contractual: state in the sale contract which discharge terms the freight includes (liner terms or free out), and require the seller to forward the carrier’s destination charge schedule with the shipping advice.
CFR against FOB, CIF and DAP
CFR sits mid-ladder in the maritime Incoterms family. Against FOB, the risk point is identical — on board at origin — but CFR adds the freight to the seller’s cost duty, which suits buyers without their own freight contracts or volume leverage with carriers. Against CIF, the only difference is insurance: CIF obliges the seller to procure minimum cover (Institute Cargo Clauses C by default), CFR obliges nobody. Against DAP, the difference is bigger: DAP moves risk to the named destination place, so the seller carries sea risk and typically insures; CFR leaves sea risk with the buyer from loading.
For glass jar programmes the choice usually resolves on two questions. First, who has better freight rates — if the buyer’s forwarder beats the seller’s carrier, FOB wins; if not, CFR simplifies. Second, who wants control of insurance — buyers with established open covers often prefer CFR or FOB and insure themselves; one-off buyers frequently prefer CIF for the bundled minimum cover.
When CFR is the right call for glass buyers
CFR fits three profiles well. New importers without carrier contracts get a landed-port price from one invoice and one point of contact. Buyers in markets where the seller’s carrier has strong service lanes (for example Ningbo–Rotterdam or Shanghai–Jebel Ali) capture rates they could not negotiate alone. And buyers whose own cover is already in place avoid paying twice for insurance they do not need. It fits poorly when the buyer’s forwarder consolidates multiple suppliers’ cargo in one container — then FOB at origin with buyer-controlled stuffing is cleaner.
How GlassPacker quotes CFR
Every GlassPacker CFR quotation states the destination port, the freight validity window (usually 30 days against volatile spot rates), the discharge terms included, and the packing specification — carton dimensions, gross weight and pallet configuration — so the buyer’s broker can pre-clear. We pair CFR with a CIF alternative on request, and samples of any jar programme ship in 7–10 days so freight decisions are made against real cartons, not assumptions. Ask for both quotations side by side; the difference line is exactly your insurance decision.
The GlassPacker CFR data file: declaration, duties, cost ladder
Duty and declaration data first: every GlassPacker CFR quotation carries the same five-number block — HS code 7010, per-carton gross weight, packed carton dimensions, pallet count and an MOQ of 1,000 pieces per size — plus a 7–10 day sample window. Glass containers under HTS 7010.90 enter the US at a duty-free general rate; China-origin cargo can still carry additional trade-measure duties that move with policy, so we fix HS code and origin at quotation and your broker confirms the current add-on in one call.
The CFR cost ladder: we book and pay the main carriage to the named port, but insurance stays yours — that gap is the clause buyers miss most. Unloading, terminal handling, demurrage risk and import duties also sit on your side. Because we contract the carrier while your policy covers the sea leg, any casualty claim runs on your insurance with the carrier's paperwork we obtain in support.
CFR questions buyers ask us
Does a CFR price include marine insurance?
No. Under CFR the seller has no obligation to insure; the buyer carries sea risk from loading and should arrange cover before sailing. If you want bundled minimum cover, ask for CIF instead — and compare both against the stock jar and bottle shapes we quote for container orders. Because risk passes before the voyage ends, buyers pair CFR with our breakage-prevention packing spec when insuring the cargo.
Who pays terminal handling charges at the destination port under CFR?
It depends on the discharge terms inside the seller’s freight contract. Liner terms usually include discharge; free-out terms push THC and discharge costs to the buyer. Always confirm in writing before comparing CFR prices — send us the terms you were quoted and we will state what our CFR price includes.
Is CFR suitable for containerised glass jars?
Yes, provided the buyer insures the cargo and the contract states discharge terms. For fragile cargo we also recommend specifying pallet configuration and carton gross weight in the sale contract so the insurance value and handling instructions match the actual load.
Leave a comment
No comments yet — be the first to share your thoughts.